
GHG Emissions · Part 3 of 4
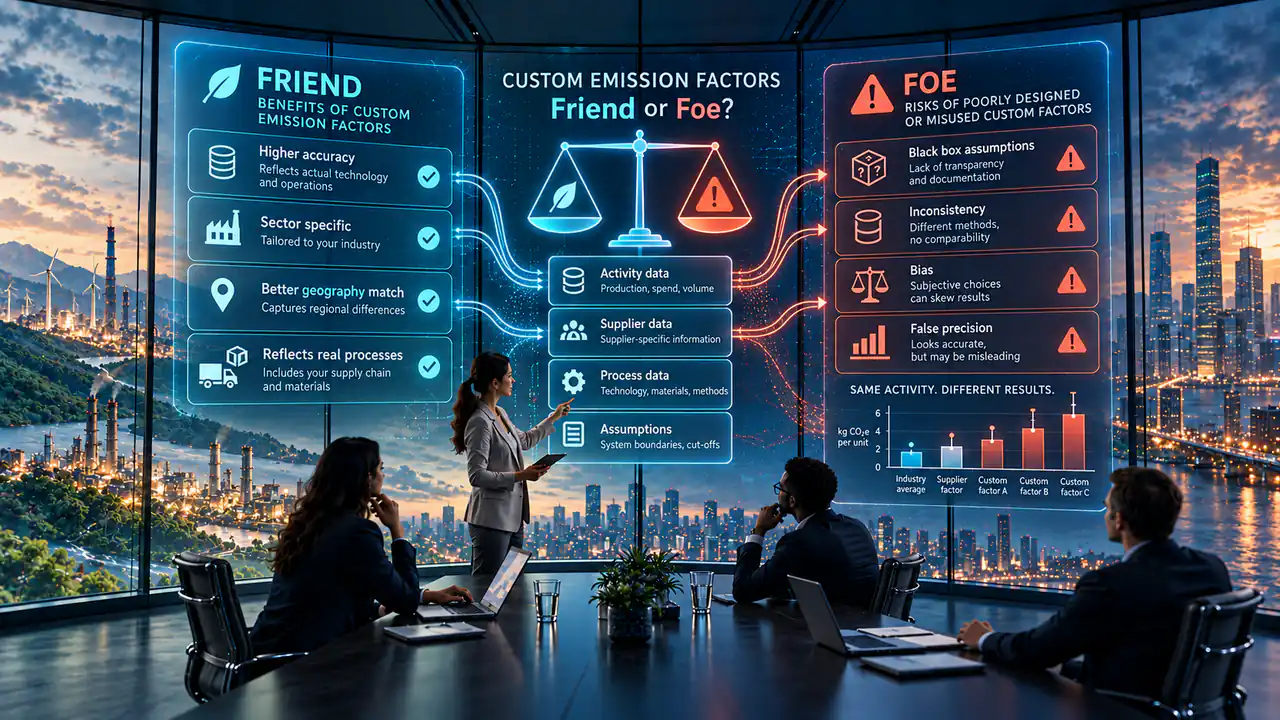
Custom Emission Factors: Friend or Foe?
Ask a sustainability team whether it would rather use a supplier’s own emission factor or an industry average and the answer usually comes quickly. The supplier’s figure describes the actual product, made in the actual factory on the actual energy mix. An industry average describes nobody in particular. Surely the specific number is the better one?
Often it is. Supplier-specific data can reflect the production process, energy sources and operating conditions behind a purchase in a way no average can. It can distinguish one supplier from another, show whether a supplier’s emissions intensity is falling and give procurement something concrete to act on. The GHG Protocol’s Category 1 guidance lists its supplier-specific and hybrid methods ahead of the average-data and spend-based methods, in order of how specific each is to the individual supplier.
The same guidance then adds a qualification that is easy to read past: a method can be more specific without being more accurate. This article is about the distance between those two properties: when a custom emission factor genuinely improves a Scope 3 inventory and when it adds precision that the data underneath cannot support.
More specific is not automatically more accurate
Consider a simple case. A supplier reports a factor of 0.52 kgCO2e per unit for a component whose industry-average factor is 0.75. The natural reading is that the supplier is about 30% less carbon-intensive than its sector and that adopting its figure makes the inventory both lower and more accurate.
Either conclusion may be right; neither follows from the two numbers alone. The comparison assumes that the supplier’s figure covers the same emissions sources as the average, over a comparable boundary and period, for the same product. It assumes Scope 1 and Scope 2 were treated the same way, fugitive emissions were included and every relevant site was counted. If any of those assumptions fails, the gap between 0.52 and 0.75 describes the data rather than the supplier.
The GHG Protocol says as much. Box 1.1 of its Scope 3 calculation guidance, on the difference between data specificity and data accuracy, notes that the supplier-specific and hybrid methods may not produce results that more accurately reflect a product’s contribution to the reporting company’s Scope 3 emissions; data collected from a supplier may actually be less accurate than industry-average data for a particular product. Accuracy, the box explains, derives from the granularity of the emissions data, the reliability of the supplier’s data sources and the allocation techniques used, if any.
A more precise number is not necessarily a more accurate number.
A factor is the end of a chain
A custom emission factor is not an independent measurement. It is the last step of a chain that begins in the supplier’s operations: activity at each site is recorded, the records are compiled into an emissions inventory, the inventory is divided by some measure of output and the result is passed to the customer, who multiplies it by the quantity purchased.
Every step inherits what came before it. A source that was never recorded at site level is absent from the inventory, therefore from the factor and therefore from the customer’s Scope 3. Nothing at the end of the chain reveals the gap.
Where the Factor Comes From
The Factor Inherits the Inventory
Inside the supplier
What the customer receives
01
Supplier operations
Sites, processes, equipment and the emissions they actually produce.
02
Data collection
What each site records, in which units and by whom.
03
Emissions inventory
The supplier’s own Scope 1 and 2, built from whatever was collected.
04
Custom emission factor
The inventory divided by a measure of output and passed to the customer.
05
Customer Scope 3
The factor multiplied by the quantity purchased.
A weakness upstream can travel through every downstream calculation. The customer receives one number, formatted the same way whether the inventory behind it is complete or not.
The missing emissions problem
Refrigerants are the clearest example, because they are easy to overlook and potent when released. Take a chilled-food manufacturer that provides a company-specific factor built from its electricity bills, its fuel records and its production volumes. Each input is well documented and the factor looks complete.
Whether it is complete depends on questions nobody may have asked. Does the company operate refrigeration systems, as a chilled-food business almost certainly does? Are refrigerant top-ups recorded? Is there an inventory of the equipment and the gases it holds? Are the individual gases identified, given how widely their global warming potentials differ? Are fugitive emissions quantified at all and at every facility?
A single top-up does not establish how much refrigerant escaped. Repeated replenishment of the same system, however, is an important indication that losses are occurring and should be investigated and accounted for. The hybrid method in the calculation guidance lists process and fugitive emissions among the allocated Scope 1 and Scope 2 data it asks suppliers to provide, so their absence is a gap in the data rather than a feature of the method.
Worked Illustration
The Apparently Complete Inventory
A Chilled-Food Supplier’s Factor
HypotheticalSupplied to the customer
Supplier-specific factor
kgCO2e per tonne of product
- Documented
Electricity
Monthly utility bills, in kWh
- Documented
Fuel
Diesel for boilers and standby generators
- Documented
Production
Tonnes of product, the denominator
- Not asked
Refrigerants
Chillers, cold stores and blast freezers
What would settle the question
- Refrigeration systems operated on site
- Top-ups recorded by a service contractor
- An inventory of equipment and the gases it holds
- Individual gases identified, since their warming potentials differ widely
- Every facility covered, including smaller ones
A custom factor cannot compensate for an emissions source that was never captured in the underlying inventory.
Hypothetical supplier. Refrigerant purchases do not by themselves measure a leak, since gas is also bought to charge new equipment or held in stock; repeated top-ups of the same system are a reason to investigate losses and account for them.
The people collecting the data matter
None of this implies that suppliers are careless. Most organisations do not have a sustainability specialist at every site. The data behind a supplier’s factor is often gathered by finance, procurement, facilities teams, plant managers or administrative staff who are diligent at their own work and have never been trained in greenhouse gas accounting. A questionnaire that seems precise to the person sending it can be ambiguous to the person answering it.
Fuel type is a routine example. A request for diesel consumption may be answered from records that say B7, biodiesel, mineral diesel or simply diesel, and the site may have no consistent way to establish what was actually purchased or burned. Each answer implies a different factor and a different treatment of the biogenic share. The way fuel is bought varies too: one site uses fuel cards, another reimburses employee claims, a third pays from petty cash and a fourth buys through central procurement.
Electricity is no different. One facility reports kilowatt-hours, another reports expenditure and a third sends the utility bill. Combined into a single factor, these answers produce a number that looks as precise as any other while resting on several different measurement methods.
One Request, Five Answers
One Factor, Five Measurement Methods
“Please provide your diesel consumption for the year”
HypotheticalSite A
Litres from fuel-tank dips
QuantitySite B
Fuel expenditure from the ledger
MoneySite C
Estimated from generator run hours
EstimateSite D
Fuel-card statements
QuantitySite E
Petty-cash receipts
Money
Combined into
One supplier factor, to three decimal places
Hypothetical sites. Each record is a reasonable answer to the question as the site understood it; the tones group them by what they measure, not by quality. Money has to be converted to litres at some price, and an estimate rests on assumptions that travel with it unrecorded.
Turning answers like these into a reliable factor takes consistent definitions, boundaries, reporting periods and units; documented assumptions; validation and reconciliation against evidence that is retained; and some form of review. These are ordinary controls. They are also the difference between asking for data and collecting it.
A data request is not the same as a data collection system.
Which part of the supplier is in the factor?
Size creates a different problem. Take a hypothetical telecommunications company supplying connectivity services. Its operations include data centres, a headquarters, regional offices, customer-facing stores, network infrastructure, warehouses, technical facilities and temporary sites. It offers its customers a factor calculated as total company emissions divided by total revenue.
That is a legitimate number. What it represents is less clear. It contains the energy of data centres the customer may never use, the offices of business units unrelated to the service purchased and the network operations that are related to it. Whether that mixture represents the purchase in proportion depends on how closely the company’s overall activity resembles the service being bought.
The problem is sharper still for diversified groups, which are common in Malaysia. A single listed group may run plantations, property development, manufacturing, logistics and hospitality through many subsidiaries, each with its own emissions profile and its own relationship between emissions and revenue. Dividing the group’s total Scope 1 and Scope 2 emissions by group revenue produces one average across all of them. Applied to a purchase from one subsidiary, that average can be wrong by a wide margin in either direction: a low-emission services business inherits the emissions of the group’s mills, while an energy-intensive manufacturing unit has its emissions diluted by revenue from property sales. The factor is arithmetically correct and describes no business the customer actually buys from.
The calculation guidance ranks supplier data by specificity: product-level data first, then data for the activities, processes or production lines that make the product, then facility-level, business-unit-level and finally corporate-level data. It advises companies to seek data as specific as possible to the product purchased. A revenue-based corporate factor sits at the bottom of that ranking without being invalid; where a supplier’s activity is homogeneous it may be entirely reasonable. The question is whether the boundary and the denominator represent the purchased good or service. Where they do not, emissions have to be allocated, and the guidance notes that allocation can add a considerable degree of uncertainty depending on the method used.
Absolute emissions and emissions intensity
A custom factor is almost always an intensity: emissions divided by something. Absolute emissions and emissions intensity respond to different forces, and a factor can move for reasons unrelated to how carbon-efficient the supplier has become.
Most suppliers have some emissions that rise and fall with production and some that are broadly fixed, from offices, building services and plant that runs regardless of throughput. If output doubles while the fixed part stays roughly constant, emissions per unit fall although no process has changed. Revenue denominators add another layer, because price increases, currency movements or a shift in product mix can move revenue with no change in physical output. Units of product, tonnes, production output and revenue are all used as denominators, and each answers a slightly different question.
Worked Illustration
Why Intensity Can Move
Same Process, Double the Output
HypotheticalFixed emissions
Buildings, offices, idle plant
Production emissions
Rise and fall with output
Output or revenue
The denominator
Year 1 · 1,000 t of product
1,000 t CO2e · 1.00 per tonne
Year 2 · 2,000 t of product
1,600 t CO2e · 0.80 per tonne
Absolute emissions up 60%, intensity down 20%. The factor improved because the fixed emissions were spread over more output; the process itself emits exactly what it did.
Hypothetical figures, not supplier data. A revenue denominator adds a further source of movement: price, currency and product mix can change revenue with no change in physical output.
A factor can change because the business changed, because the denominator changed or because the emissions changed. These are not the same thing.
The problem of comparability
Everything so far concerns one supplier’s factor. The difficulty sharpens when two are placed side by side. Supplier A reports 0.85 kgCO2e per unit, Supplier B reports 0.52 and the product is nominally the same. Before that difference informs a purchasing decision, the two factors need to rest on bases consistent enough to compare.
B’s lower figure may reflect a genuinely more efficient operation. It may equally reflect a factor that omits refrigerants, covers a year of unusually high output or divides corporate emissions by revenue where A divides site emissions by units. The calculation guidance asks for supplier data covering, as far as possible, the same period as the reporting company’s inventory, together with a description of the methodologies and data sources used. Those requests exist because the number alone cannot show whether the comparison is fair.
Before the Comparison
Two Factors, One Product
Factors as reported
HypotheticalSupplier A
0.85
kgCO2e per unit
Supplier B
0.52
kgCO2e per unit
On its face, Supplier B is 39% less carbon-intensive. Whether that is true depends on:
Same boundary?
Site, business unit or whole company
Same period?
And the same period as the customer’s inventory
Same sources?
Fugitive and process emissions included in both
Same methodology?
Including how emissions were allocated
Same product?
The same specification, not the same category
Same denominator?
Units, tonnes or revenue
Comparable data quality?
Measured, estimated, reviewed or assured
A number cannot support a meaningful comparison unless the basis of comparison is sufficiently consistent. Until these are answered, the gap may describe the suppliers or it may describe their data.
Custom factors and internal carbon pricing
The stakes rise when supplier factors feed commercial decisions. Some organisations apply an internal carbon price, a notional cost per tonne of emissions, when assessing investments, products or purchases. IFRS S2 does not require a company to adopt one; it does require a company to explain whether and how it applies a carbon price in decision-making and to disclose the price it uses, so for companies reporting under the standard the practice is becoming visible outside the business as well as within it.
In principle, supplier-specific data lets procurement weigh purchase price plus carbon cost rather than purchase price alone. One supplier may be cheaper and more emissions-intensive, another dearer and less so. A carbon price makes that difference financially visible and, at a high enough price, can change which supplier wins. That only works if the factors are reliable and comparable. Multiplied by a carbon price, an emissions figure becomes a cost, and a cost that enters a tender evaluation carries every weakness of the factor behind it.
Worked Illustration
Purchase Price Plus Carbon Cost
Internal carbon price RM 150 per tonne
HypotheticalOn the factors as reported
Supplier A
RM 112,000
RM 100,000 + 80 t × RM 150
Supplier BLower
RM 111,500
RM 104,000 + 50 t × RM 150
With B’s refrigerant losses included
Supplier ALower
RM 112,000
RM 100,000 + 80 t × RM 150
Supplier B
RM 114,500
RM 104,000 + 70 t × RM 150
20 tonnes missing from one factor change which supplier wins. The internal price did its job; the factor it was applied to did not.
Hypothetical prices, emissions and carbon price, for illustration only. The bars start at zero, so most of each is purchase price; the decision turns on the small part that is not.
The supplier that reported less completely looks cheaper on a carbon-adjusted basis, and the supplier that reported more thoroughly is penalised for it. Nobody intended that outcome; it follows arithmetically from treating two factors as comparable when they were not.
A questionable emission factor can distort a financial purchasing decision.
A time series, not a snapshot
The upside is real. Good supplier data shows a company where its supplier emissions are concentrated, which suppliers to engage on reductions and whether emissions performance should weigh in procurement. Tracking performance and engaging value chain partners are, the calculation guidance notes, among the reasons companies most often give for building a Scope 3 inventory. It also recommends asking suppliers what share of a factor rests on primary rather than secondary data, so that the ratio can be tracked as their assessments mature.
A single year’s factor says little about progress. The value appears when the same supplier reports on the same basis in 2026, 2027, 2028 and 2029 and a change in the factor can be traced to a change in the operation. If the supplier redraws its boundary, adds a source it previously omitted or switches from revenue to units midway through, the series breaks and the customer needs to know which years remain comparable.
That is the same discipline that governs restating GHG emissions in a company’s own inventory. A methodology change is not a problem in itself; an unidentified one is. The same applies when a supplier’s factor replaces a spend-based estimate in the customer’s inventory: the expenditure it replaces has to leave the spend-based calculation at the same moment, or the purchase is counted twice, which is the subject of the second article in this series, on Scope 3 double counting.
A custom factor becomes much more valuable when it is part of a consistent time series rather than a one-off number.
Standardised factors are not the poor alternative
None of this makes modelled or standard factors a fallback to discard as soon as supplier data arrives. Robust factor sets are built systematically. They can reflect country and regional differences, sector characteristics, energy systems, economic structures and production relationships, and spend-based sets can be adjusted to the right price year. The first article in this series, on spend-based Scope 3 emissions, set out how much depends on applying them correctly.
A standard factor is not specific to any one supplier. What it offers instead is one consistent methodology across thousands of transactions, which a collection of supplier factors built on different boundaries cannot. The two have different strengths and different weaknesses, and a well-constructed inventory usually uses both.
Modelled or standard factor
Potential strengths
- Consistent across every transaction
- Scalable to a full ledger
- Comparable by construction
- Available where supplier data is not
Potential limitations
- Not specific to one supplier
- May not reflect a particular facility or product
- Rests on sector-average or modelled assumptions
Supplier-specific factor
Potential strengths
- Specific to the supplier and potentially the product
- Can reflect actual energy sources and processes
- Can track a supplier’s performance over time
- Supports engagement and procurement
Potential limitations
- Only as good as the supplier’s data
- Boundaries and methods vary between suppliers
- Sources can be missing without trace
- Can be hard to audit or reproduce
When a custom factor is a friend
A custom factor earns its place when it relates to the product or service actually purchased, over a clearly defined boundary that includes the sources that matter. It helps when it covers an appropriate reporting period, when its methodology is documented and when the data beneath it is complete enough that the calculation could be explained and, in principle, reproduced by someone else.
It becomes more useful again when it is built on the same basis as the factors it will be compared with, when changes from one year to the next can be explained by changes in the operation and when it has been reviewed or assured to a degree proportionate to the decisions it will support. The calculation guidance recommends asking suppliers whether their data has been assured or verified and giving preference to verified data; it does not make assurance a condition of use.
Where those conditions hold, a supplier’s factor is a better description of the purchase than any average can be. Where they do not, the average may be the more defensible number, and the better course is to use it while working with the supplier to close the gaps. Geography raises a further limit on specificity: even a well-built supplier factor describes one tier of a supply chain that may span several countries, which is the subject of the final article in this series.
Neither friend nor foe
Custom emission factors are neither inherently a friend nor inherently a foe. They are a tool, and their value depends on whether the data behind them is good enough to justify the additional specificity. The objective is not to collect the most specific number available. It is to use the most appropriate number that can be supported by sufficiently reliable evidence.
The ultimate value of better supplier data is not a more elaborate inventory. It is the ability to understand where emissions come from, to see whether suppliers are improving and to make better-informed decisions about the value chain.
Precision is useful. False precision is not.
References
- GHG Protocol, Technical Guidance for Calculating Scope 3 Emissions, Introduction, on primary and secondary data, the levels of supplier data ranked by specificity (reproducing Table 7.7 of the Scope 3 Standard) and the business goals of a Scope 3 inventory; and Category 1, on the four calculation methods, Box 1.1 on data specificity and data accuracy, the data to request from suppliers under the supplier-specific and hybrid methods and the preference for verified or assured data.
- GHG Protocol, Corporate Value Chain (Scope 3) Accounting and Reporting Standard, Chapter 7, on data quality and collecting primary data, and Chapter 8, on allocation, as referenced by the calculation guidance.
- IFRS Foundation, IFRS S2 Climate-related Disclosures, paragraph 29(f), on disclosing whether and how an entity applies an internal carbon price in decision-making and the price it uses.
Ace CSR supports Malaysian companies with Scope 3 assessment, GHG accounting and sustainability reporting, including supplier data requests, the review of supplier-specific factors and the methodology notes that explain which factor was used where.
Explore More
Deciding whether to rely on supplier emissions data?